
Mortgage affordability is top of mind for many Toronto, Etobicoke and Mississauga homeowners
Remember when buying a house felt like making it?
You got the keys, took approximately 37 photos on the front porch, and thought, “We did it!”
Fast-forward a few years, and your house has developed expensive hobbies. Property taxes. Insurance. A water heater that chooses violence on Thanksgiving weekend.
And suddenly, your biggest financial asset is also the most demanding person in your life.
Your mortgage isn’t the whole story
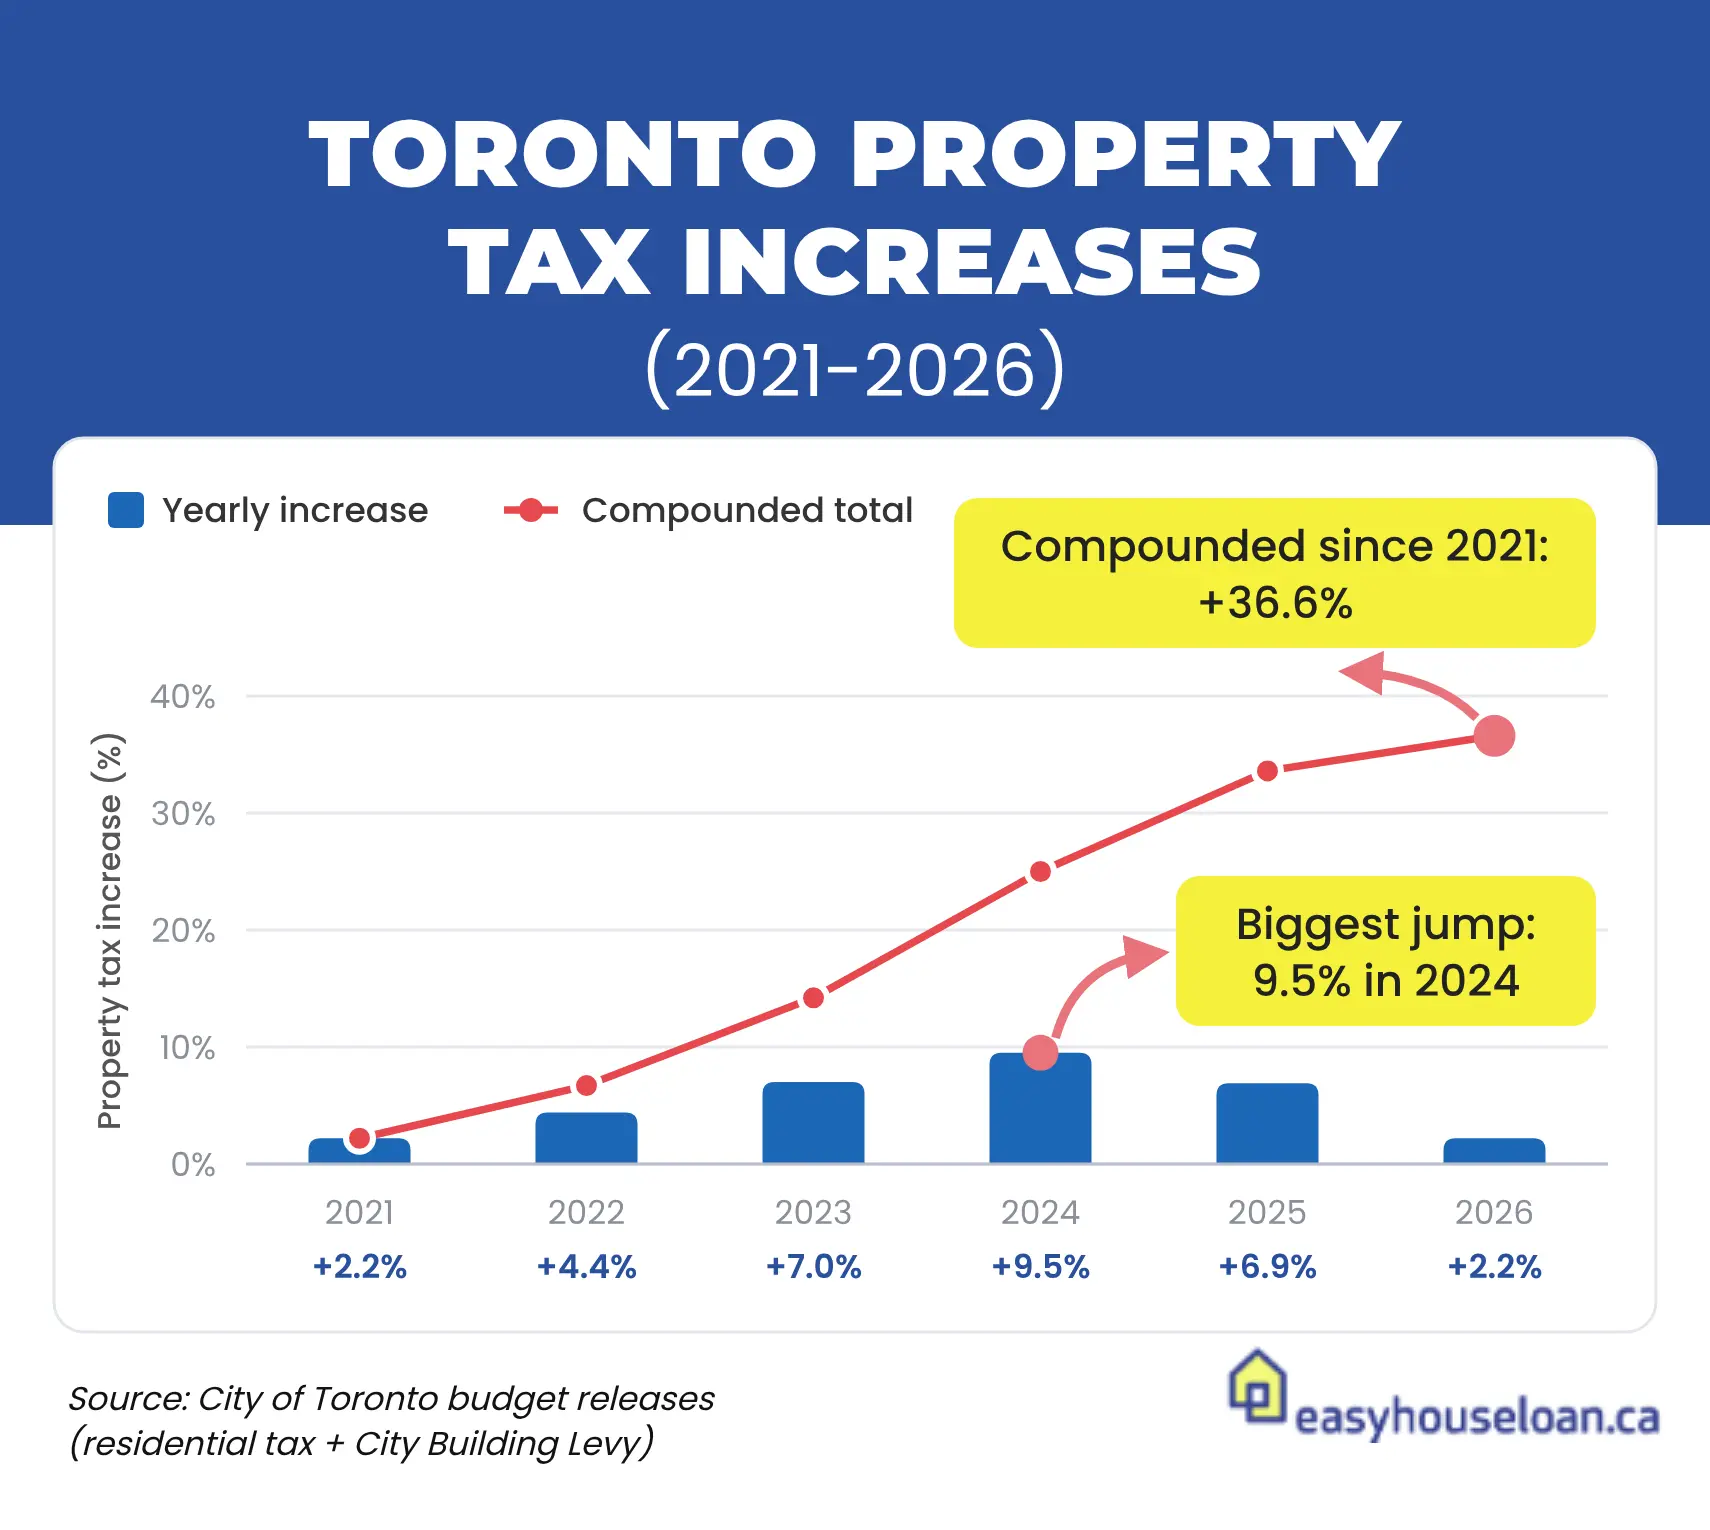
Remember home ownership has a supporting cast: property tax, insurance, heat, condo fees and repairs all creep upward, and none ask permission. Toronto homeowners saw property taxes jump 9.5% in 2024, 6.9% in 2025 before a gentler 2.2% this year. That’s it’s own horror story in the making.
A good rule of thumb? If you’re regularly putting groceries, utility bills or home repairs on a credit card because your mortgage has swallowed your cash flow, it’s time to take a closer look.
Lenders use debt and housing-cost ratios to assess affordability, but qualifying for a mortgage and comfortably affording one are two very different things. Especially true if you’re self-employed, earn commissions or have an income that changes from month to month.
Guidelines for a Comfortable Mortgage Budget
| Level | GDS (Housing % of Income) | What It Means |
|---|---|---|
| Conservative / Safe | 25% – 32% | Leaves plenty of room for savings, lifestyle, and unexpected expenses. |
| Lender Maximum (Standard) | Up to 39% | The threshold most banks use for approval. |
| Total Debt Maximum | Up to 44% | Includes housing plus all other monthly debt repayments combined. |
Try our mortgage calculator here
What can you do about mortgage affordability concerns?
First, don’t panic. Second, don’t wait until you miss a payment to ask for help. Depending on your situation, options include:
- refinancing at renewal
- stretching your amortization
- renting out a room or basement suite
- a short-term private mortgage can also bridge a rough patch, as long as there’s a clear plan to get back to a regular lender.
The right fit depends on your mortgage terms, equity and goals. Steer clear of anyone promising an instant fix or charging upfront fees to “save” your home.
Let’s Make Homeownership Feel Good Again
If your mortgage is starting to feel heavier than it used to, let’s review your options.
Because home is where the heart is. Your entire paycheque doesn’t have to live there, too.