
With interest rates trending down and inflation cooling, 2025 could be a smart time to reassess your mortgage, especially if you’re feeling the pinch of monthly payments. Refinancing can help you:
- Lower your interest rate
- Reduce your monthy payment
- Consolidate debt
- Access home equity for home renos or investments
But refinancing isn’t always the right move. That’s why we built this quick flowchart. To help you make a smart move, not just a fast one.
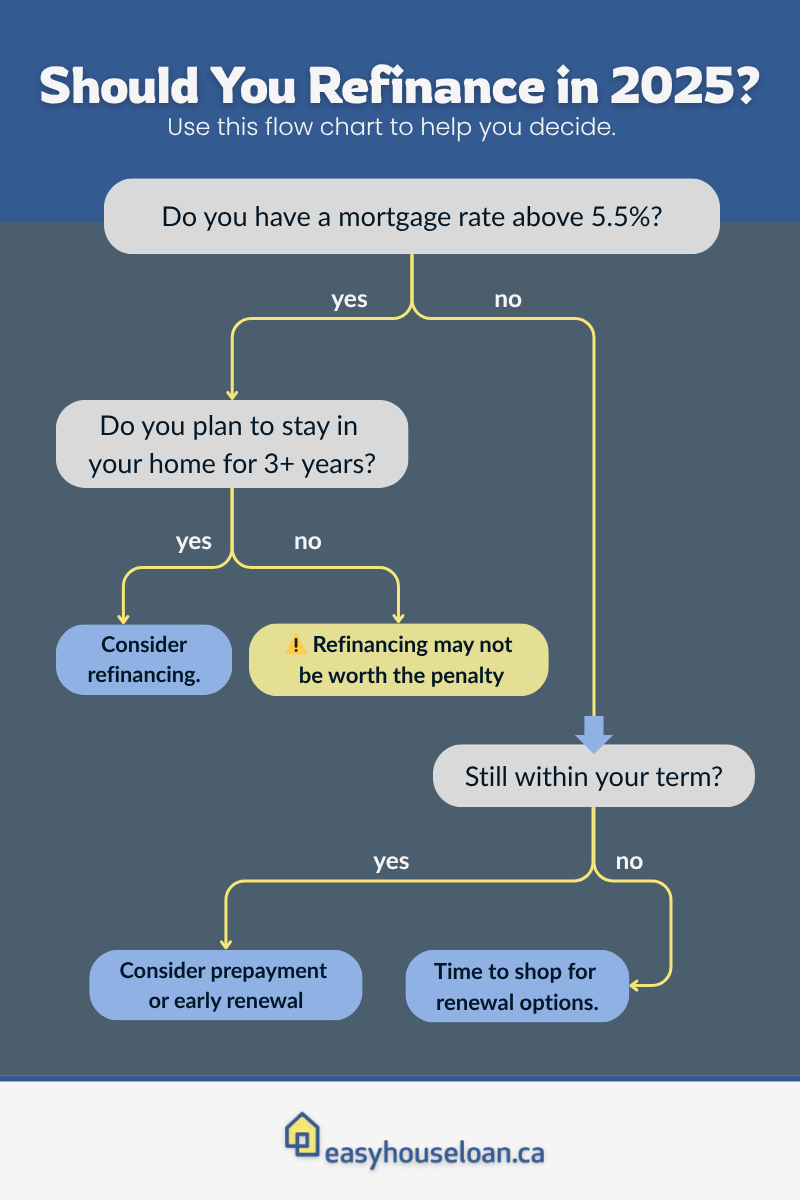
Think of refinancing as aligning your mortgage with your current reality. Maybe you locked into a five-year fixed at 5.79% during the peak panic of 2023, and now you’re watching rates trickle down like molasses in January. Or maybe you’ve built up solid equity in your home in Vaughan, Oshawa, or that long-overdue fixer-upper semi in Etobicoke, and you’re wondering if it’s time to put that equity to work.
If you’re carrying high-interest debt or planning major upgrades (hello open-concept kitchen!), refinancing could actually save you money and improve your quality of life. Yes, even if your neighbour says it’s “not worth the penalty.”
Learn more about refinancing & home equity
3 Steps to Explore Whether you Should Refinance
So what can you actually do right now?
- First, grab a recent mortgage statement and check your current rate, remaining term, and whether you’re in a fixed or variable product.
- Next, contact your lender—or better yet, reach out to someone like us—and ask for your prepayment penalty. (We promise not to judge the number.)
- Finally, if you’re in a stable job, planning to stay put for at least a few years, and your current rate is over 5.5%, it’s probably worth running the numbers.
A good broker can simulate a break-even scenario to show you exactly how long it would take to recoup the cost of switching. Think of it like switching phone plans, only this one could save you thousands instead of just a few extra GBs of data.
Know someone else trying to navigate today’s market? Book a Refinance Strategy Call with Easyhouseloan.ca. No pressure, just clarity.