
If you’ve been Googling mortgage advice lately, you’re not alone. We’ve been getting the same handful of questions from homebuyers, sellers, and homeowners all across the Greater Toronto Area, and they line up exactly with what people are searching for online.
So, let’s tackle them head-on. No jargon, no crystal balls.
1. Should I lock in my mortgage rate right now?
If you’re on a variable rate, the Bank of Canada’s recent rate cuts may have you feeling a little less pressure in your monthly budget. That’s a good thing.
But locking into a fixed rate in 2025 is a balancing act:
- Why lock in now? You want payment stability and peace of mind if rates unexpectedly rise again.
- Why wait? Fixed rates are still expected to drift lower over the next year as bond yields soften.
Pro tip: Don’t decide in a vacuum. Look at your remaining term, prepayment penalties, and how long you plan to stay in your current home. Sometimes, waiting a few months is worth thousands. Sometimes, locking now keeps you sleeping better at night.
2. “Am I going to get approved? I don’t want to pay for an appraisal if I’m not.”
We can’t give you a guaranteed “yes” without seeing all your documents first, and neither should anyone else. If a broker promises approval before reviewing your full file, that’s a huge red flag.
Here’s why: Mortgage approvals depend on a mix of factors—income, credit history, debt load, property type, and more. An appraisal is just one piece of the puzzle, but lenders will only accept valuations from an independent appraisal company.
Yes, they can be pricey, but skipping the step could mean delays or surprises later. The smart move? Get your paperwork in early so we can give you the clearest picture possible before you spend a dime on an appraisal.
Pro Tip: Tidy up and tackle small repairs before the appraiser arrives. While they won’t be judging your décor, a well-maintained home can leave a better impression and help ensure the valuation reflects its true potential.
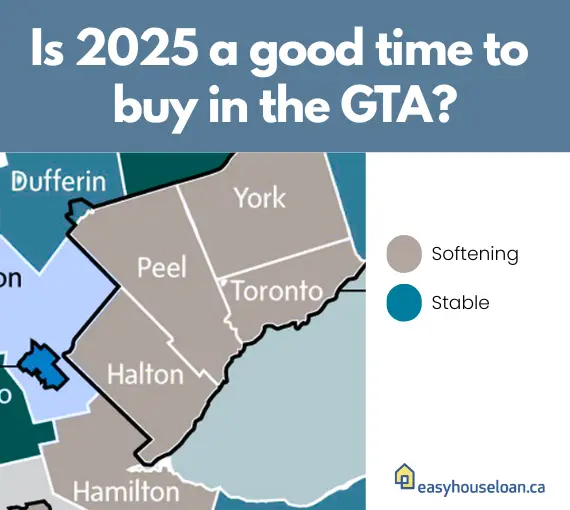
3. Is 2025 a good year to buy in the GTA, or should I wait?
The million dollar, most-asked mortgage question. And it depends on your readiness, not just the market.
Hamilton
There has been a 4.6% decrease in the price of homes since last year.
Brampton
There has been a 8.6% decrease in the price of homes since last year.
Halton
There has been a 13.2% decrease in the price of homes since last month.
Mississaugua
There has been a 5.7% decrease in the price of homes since last year.
Right now, buyers have more breathing room than in the bidding-war madness of 2021–2022. Inventory is increasing, sellers are negotiating, and you’re less likely to face 15 competing offers.
- Why buy now: You’re financially prepared, pre-approved, and ready to stay in the home for 5+ years.
- Why wait: You’re still saving for a down payment or your employment/income situation could improve in the next year.
Pro tip: Even if you think you’re “waiting,” get pre-approved now. That way, you can move fast when the right property hits the market.
The Bottom Line
The GTA market is shifting in ways we haven’t seen in years. Whether it’s locking in a rate, getting your condo appraised, or deciding when to buy, the “right” answer is always personal.
If you want to know what makes sense for you, not just “the market, ”we’re happy to walk you through your numbers, your options, and your timing.